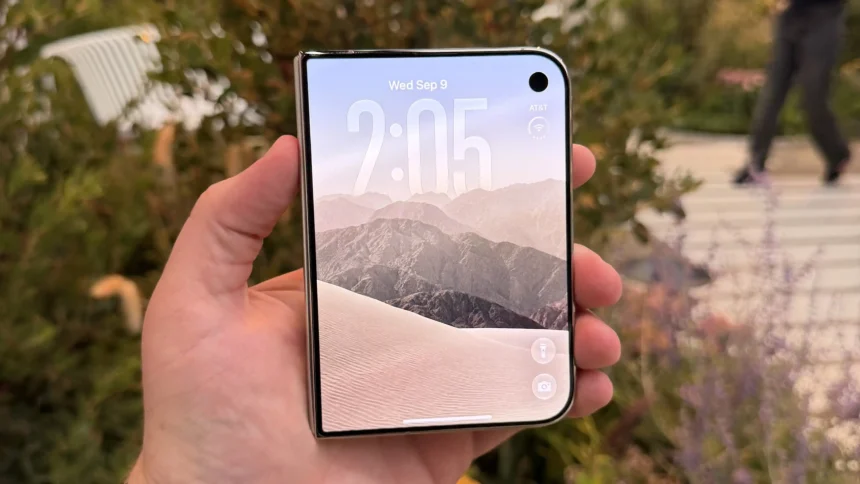
The global smartphone industry stands at a critical threshold where physical display innovation meets long-term market consolidation across supply chains. For several years, flexible screen adoption has remained confined to early adopters willing to accept hardware trade-offs for novel form factors. Recent market forecasts indicate that major new vendor entry into the foldable display market will fundamentally reshape component manufacturing scale, procurement allocations, and vendor share. Rather than simply splitting current demand, the arrival of high-volume ecosystem players accelerates panel orders and establishes clear reliability standards. According to research published by Counterpoint Research , display foundries are transitioning from niche fabrication into a consolidated commercial era marked by aggressive supplier realignment through 2030.
This multi-year evolution highlights how panel manufacturing scale, chemical substrate durability, and software optimization directly intersect in modern mobile engineering. Early folding devices faced distinct structural limitations, including persistent crease depth, delicate protective layers, and severe thermal management constraints. As manufacturing yields improve and ultra-thin glass formulations mature, specialized production facilities are converting cleanrooms into high-volume manufacturing hubs. Consequently, updated projections show that unified hardware ecosystems will trigger an immediate redistribution of panel allocations, forcing incumbent leaders to adapt component strategies.
Initial shifts in the foldable display market
The near-term introduction of new premium folding hardware will alter competitive dynamics among global device manufacturers. Projections for 2026 indicate that Apple will capture a 27 percent share of total foldable smartphone panel shipments during its initial market entry. This rapid initial presence relies on heavy advance component orders designed to build global launch inventory across tier-one retail channels. Meanwhile, Samsung is forecast to lead 2026 shipments with a 33 percent market share, backed by an 8 percent year-over-year shipment increase.
In contrast, Huawei is expected to rank third in 2026 with a 25 percent share after a 6 percent annual shipment decline. This initial baseline exposes immediate market share compression for incumbent manufacturers who previously operated without high-tier competition in the flexible screen sector. Fabrication plants face complex operational challenges balancing internal division orders against massive external commitments. For display suppliers, fulfilling primary high-volume orders requires dedicated cleanrooms, strict defect tolerances, and optimized lamination processes to survive repetitive fold cycles.
Long term vendor market share redistribution
Looking beyond initial market entry, overall foldable panel shipments are forecast to grow by 74 percent between 2026 and 2030. This expansion reflects a compound annual growth rate of roughly 15 percent, establishing flexible displays as a key hardware sector. The primary driver of this trajectory is Apple, whose panel shipments are forecast to grow 167 percent from their H2 2026 baseline through 2030. That growth would elevate Apple to a 42 percent global market share by the end of the decade.
Such sustained scale by a single buyer will fundamentally redefine the market position of established rivals. Samsung is expected to increase panel shipments by 27 percent by 2030, yet its overall market share will drop from 33 percent to 24 percent. Similarly, Huawei is forecast to see a modest 3 percent shipment increase over the same four-year span, causing its market share to contract to 15 percent. As examined in studies on global smartphone production growth , hardware scale in premium tiers grants major pricing power over key components, forcing competitors to alter margins.
Form factor evolution and mechanical convergence
The underlying engineering of flexible display panels is also undergoing a decisive transition through 2030, driven by shifting consumer preferences. In-fold display panels are projected to grow shipment volume by 79 percent between 2026 and 2030. This expansion will solidify their market dominance, raising their total shipment share from 81 percent to 84 percent. The persistent preference for in-fold designs underscores consumer demand for expanded tablet interfaces that protect sensitive optical layers when folded.
At the same time, multi-fold panel architectures are forecast to experience the highest growth rate across the display industry. Multi-fold shipments are expected to grow 179 percent by 2030, raising their market share from 2.8 percent to 4.5 percent. Although multi-fold devices remain technical niche products due to complex dual-hinge mechanisms, their expansion demonstrates rising commercial viability. Conversely, clamshell panel shipments will grow 27 percent in absolute volume, yet their relative market share will fall from 16 percent to 12 percent.
Engineering constraints of compact clamshell panels
The relative decline of clamshell market share highlights persistent physical limitations inherent to compact flip-style devices. Clamshell smartphones offer spatial convenience by folding standard screens in half, but they do not deliver expanded screen area for productivity or media multitasking. Internal volumetric constraints also restrict battery size, camera sensor depth, and cooling assemblies compared to traditional slab hardware. In contrast, in-fold designs convert smartphones into functional tablet workstations, offering utility that justifies premium pricing.
Supply chain realities and foundry capital constraints
Meeting long-term panel demand will place immense technical and financial pressures on specialized fabrication foundries. Manufacturing flexible OLED screens requires precise polyimide substrates, high-precision laser lift-off processes, and multi-layer thin-film encapsulation to shield organic materials from degradation. Furthermore, integrating ultra-thin glass layers that withstand repeated folding stress without micro-cracks remains a capital-intensive manufacturing step. As explored in discussions on display cost structures and mobile margins , suppliers must continuously refine production yields to protect operating profitability.
This ecosystem dynamic creates an interdependent relationship between display manufacturers and primary technology brands. Foundries must commit billions in capital expenditure to build dedicated production capacity years before commercial volume yields materialize. When a major buyer places massive long-term commitments, it provides foundries with necessary scale to amortize machinery costs and optimize yield efficiency. However, high customer concentration can squeeze smaller hardware brands, which face reduced panel allocations and elevated component costs.
The long-term trajectory of the flexible screen industry signals a fundamental shift from specialized experimentation toward consolidated manufacturing scale. As dominant ecosystem buyers integrate flexible substrates across core product lines, display suppliers will prioritize high-yield contracts over low-volume custom orders. This structural realignment will define mobile hardware competitiveness for the next decade, turning display yield capabilities into a decisive operational advantage.