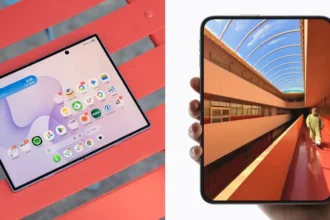
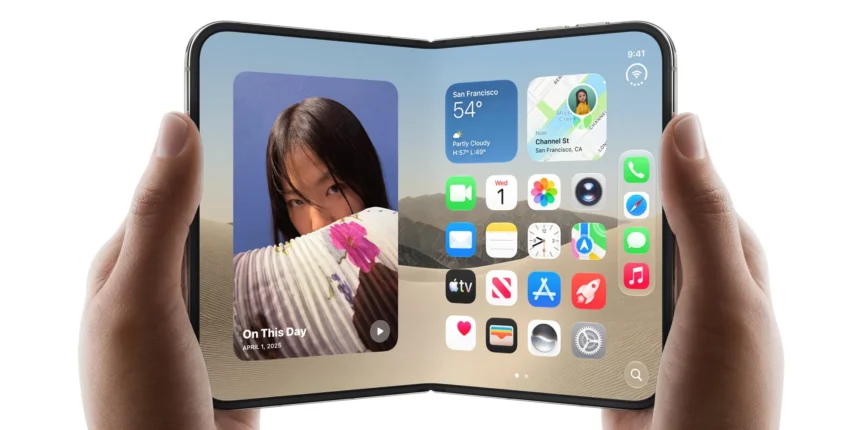
The premium smartphone sector faces a structural pivot point as flexible screen technologies transition from experimental novelties into mainstream flagship hardware requirements. Balancing component procurement expenses with corporate gross margin targets has forced major consumer electronics brands to rethink multi-year engineering roadmaps. Recent industry chatter regarding the rumored iPhone Duo display cost highlights the acute economic challenges inherent in bringing large-scale foldable devices to global consumer markets. While conventional smartphone displays have benefited from decades of glass manufacturing optimization and standardized assembly lines, flexible panels demand specialized layer stackups, custom optical clear adhesives, and intricate structural backing plates. Understanding how component pricing intersects with manufacturing constraints provides crucial insight into where high-end mobile hardware is heading. For an industry accustomed to steady annual iterations, introducing a flexible form factor requires navigating volatile supply ecosystems and immense capital investment, as explored in recent foldable display market analysis across the mobile space.
Hardware Margins and the iPhone Duo Display Cost
In premium mobile hardware, display assemblies traditionally represent one of the single largest line items on a standard bill of materials, rivaled only by advanced application processors. Unconfirmed reports circulating through global supply channels suggest that preliminary foldable screen modules for next-generation hardware could command prices near $250 per unit. If accurate, such a figure would represent more than double the procurement cost of standard high-refresh-rate OLED panels used in contemporary flagship smartphones. High baseline component expenses inevitably create tight constraints for product pricing teams, forcing companies to choose between absorbing reduced gross margins or setting retail prices well beyond established luxury tiers. Elevated baseline expenses are already reshaping high-end device strategies across the broader smartphone cost landscape today.
When a display panel accounts for such a substantial percentage of total manufacturing expenditure, hardware vendors must carefully balance other internal subsystems. Engineers are often forced to evaluate whether to compensate for panel costs by optimizing memory allocations, simplifying external chassis finishings, or leveraging shared platform components across adjacent hardware tiers. Furthermore, early production runs of complex hardware components carry elevated scrap rates, which vendors must account for within long-term financial modeling.
Substrate Yields and Exclusive Fabrication Agreements
The financial leverage in display manufacturing remains tightly concentrated among a small handful of dominant suppliers capable of producing ultra-thin glass substrate panels at commercial yield rates. Securing multi-year supply exclusivity can offer hardware vendors guaranteed volume allocation and custom design specifications, yet it simultaneously introduces single-source supply chain vulnerabilities. When a single manufacturing partner controls the primary bottleneck component, any unexpected disruption in panel yield, material purity, or optical lamination precision reverberates across the entire production schedule. Consequently, contractual arrangements in this space frequently involve delicate risk-sharing mechanisms, stepped volume tiers, and minimum yield guarantees that shape corporate strategy for multiple product generations.
Fab capacity for flexible displays requires massive initial capital expenditure, as cleanroom machinery must handle delicate multi-layer lamination processes without introducing sub-micron defects. As glass substrates become thinner to allow tighter bend radii, the risk of micro-fractures during laser cutting and edge finishing increases exponentially. Display foundries must continually refine chemical tempering processes to enhance impact resistance while maintaining flexural endurance over hundreds of thousands of fold cycles. These technical barriers restrict the market to top-tier fabricators, leaving device makers with limited negotiation leverage during initial procurement phases.
Engineering Tradeoffs in Foldable Hinge and Metallurgy
Beyond the flexible panel itself, the mechanical hinge assembly represents the primary structural engineering hurdle of any foldable device platform. Supporting a flexible display requires eliminating micro-abrasions, preventing localized stress concentrations, and managing tight bend radii without causing material fatigue over time. Integrating complex mechanical joints demands novel metallurgy and precision fabrication techniques. The adoption of 3D-printed titanium components for hinge covers underscores how modern consumer electronics borrow methods from aerospace manufacturing to achieve high strength-to-weight ratios within sub-millimeter structural tolerances. Official documentation in Apple’s press release outlines how structural engineering innovations intersect with overall device reliability standards.
Achieving extreme alignment precision in hinge construction directly protects the fragile display stack resting above the mechanical support frame. Misalignment by mere fractions of a millimeter can introduce uneven pressure distribution across the flexible substrate, leading to premature screen failure or unsightly surface creasing. Furthermore, designing internal support structures requires balancing mechanical rigidity against thermal management pathways. Custom heat spreaders and vapor chambers must articulate alongside the hinge without pinching internal ribbons or restricting heat dissipation from high-performance silicon chips.
Sustainability Metrics and Environmental Accounting
While component cost speculation often dominates tech sector headlines, verified hardware specifications highlight an equally critical vector of modern industrial design: environmental accounting. Official disclosures reveal that devices like the iPhone Duo incorporate 35 percent recycled content overall, backed by specific material mandates including 100 percent recycled cobalt in battery cells and 100 percent recycled titanium in 3D-printed hinge covers. Integrating recycled materials into precision structural components introduces complex material engineering challenges, as maintaining structural integrity requires strict supply verification and precise alloy formulation.
These material choices require extensive re-tooling of secondary supply streams and rigorous tracking across global refiners to ensure compliance with corporate decarbonization targets. Manufacturing operations for advanced mobile hardware are simultaneously shifting toward cleaner energy inputs across global supply networks. Supply chain operations responsible for assembling complex foldable architectures are increasingly mandated to run on renewable energy sources, with current benchmarks reaching 60 percent renewable electricity utilization across component fabrication and final assembly stages. Packaging design has similarly evolved to eliminate single-use plastics entirely, shifting to 100 percent fiber-based paper materials that are fully recyclable at home.
Market Realities Behind Early Component Leaks
Navigating early supply chain reports requires distinguishing between unverified market rumors and concrete corporate commitments. Information leaked from social media channels often captures real negotiations or early bill-of-materials estimates, yet these figures reflect fluid supply dynamics rather than finalized retail facts. Display pricing contracts are frequently structured around stepped volume tiers, yield performance bonuses, and rolling price adjustments over multi-year production cycles. What is cited as an initial $250 component cost during early sample phases may decline significantly as fab yields stabilize and production ramps toward commercial scale.
Furthermore, analyzing total hardware economics solely through display procurement costs oversimplifies how global technology leaders manage broad product portfolios. Higher display costs are frequently offset through vertical integration, platform services revenue, and shared component architectures across broader hardware lines. As foldable panel manufacturing matures and alternative suppliers develop competing ultra-thin glass processing capabilities, cost pressures will naturally ease.
The trajectory of foldable mobile technology ultimately hinges on resolving the tension between extreme component pricing and mass-market accessibility. As manufacturing yields improve and recycled advanced alloys lower overall material overhead, the structural economics of flexible devices will gradually align with traditional flagship standards. The ongoing evolution of supply agreements, structural engineering innovations, and green manufacturing standards signals that the foldable category is transitioning from an expensive hardware experiment into a mature, sustainable industrial platform.